

This is a product of country-specific restrictions and tax code. The problem is structural: brokerage accounts are regulated by where you live, not only by where you opened them. This article, drawing on the experience of the team at Zacks Trade, a U.S.-based online brokerage that works with international traders, explains why that happens and what to look for in an arrangement that can move with you. It covers five practical issues: account continuity, access to U.S. markets, currency, platform access, and borrowing across borders.
Moving abroad with an investment portfolio: How to stay invested across borders
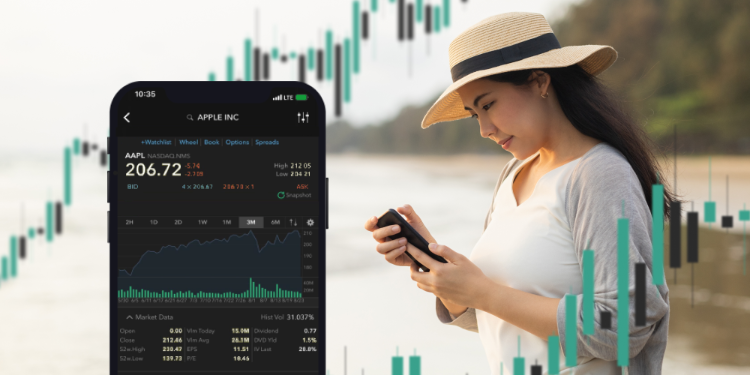
Most relocation plans are built around the things that cannot wait; residency permits, housing, schools, and a local bank account. The investment portfolio tends to sit at the bottom of the list, on the reasonable assumption that it will simply follow. For many people it does not. A few weeks after landing, a letter arrives explaining that the account has been restricted from closing trades only, or that it will be closed altogether.
In this article
1. Why accounts get closed when you move
A broker is licensed to serve clients in specific jurisdictions. When your residential address changes, three things change with it: certain regulations that apply to the account, potential tax reporting obligations, and the products you may have available to you. If a broker has no permission, appetite or infrastructure to serve residents of your new country, the simplest response is to restrict or close the account.
What to do about it
- Ask before you move, not after. Contact your broker with your destination country and ask directly whether they will continue to service the account once your address changes, and on what terms.
- Never keep a stale address on file. Leaving a former home address on an account to avoid restrictions can breach the account agreement and create tax reporting problems in both countries. Update your details honestly and plan around the answer.
- Ask how a transition would work. Some firms can continue serving you directly; others operate through affiliates in different regions and may be able to move your account without impact to the account availability. Either way, you want a written answer on whether there will be an impact on the account.
- Check the regulator and protections. Understand which regulations impact your account and what investor-protection scheme applies. Protection is determined by where the account is held, not where you live.
Join the community
Get regular tips and advice to make the most of your expat life
2. Trading U.S. markets from outside the United States
The U.S. market remains the deepest and most liquid in the world, and most expats (and most traders in general) want to keep access to it. In most cases that is possible, but the rules differ sharply depending on whether you are a U.S. person.
If you are not a U.S. citizen or resident
- Tax status is declared on Form W-8BEN. This certifies you as a non-U.S. person. Without it, U.S. dividends are generally withheld at 30%; with it, you may qualify for a reduced rate under a tax treaty between the U.S. and your country of residence.
- Watch for U.S. estate tax exposure. Non-resident aliens can be subject to U.S. estate tax on U.S.-situs assets, including U.S. shares, with an exemption of only $60,000 unless a treaty provides otherwise. This is worth raising with an adviser once holdings grow.
If you are a U.S. citizen living abroad
- You remain a U.S. taxpayer wherever you live. Filing obligations continue, including the FBAR for foreign accounts exceeding $10,000 in aggregate and, above higher thresholds, potentially Form 8938.
- Foreign funds can create tax confusion. Many non-U.S. mutual funds and ETFs are treated as Passive Foreign Investment Companies (PFICs), which carry punitive U.S. tax treatment and complex reporting. This is a key reason many Americans abroad prefer to keep investing through a U.S. brokerage in U.S.-domiciled securities.
- Local providers may decline you. Because of FATCA reporting requirements, some banks and brokers outside the U.S. choose not to open accounts for U.S. citizens. A U.S. brokerage that accepts clients living abroad can fill that gap.
3. Currency: the cost most expats underestimate
Living in one currency and investing in another creates a quiet, recurring cost. Each international wire can carry sending, intermediary and receiving fees, and the exchange rate a retail bank applies can include a markup that is easy to overlook. Across a year of salary transfers and portfolio top-ups, those costs compound.
It helps to separate two very different activities. Currency conversion is the practical need to move money between your local currency and the currency of the assets you own. Foreign exchange trading is speculating on currency movements for profit. Expats need the first; they do not need to become currency traders to get it.
What to look for
- Funding in more than one currency. Being able to deposit in the currency you earn in, rather than converting before you send, reduces the number of conversions and fees.
- Local transfer options. Ask whether you can fund and withdraw through domestic payment systems in your region (for example, SEPA in Europe, ACH in the U.S. or Faster Payments in the UK) rather than international wires.
- Transparent conversion. Ask how conversion rates are set and whether any spread is added. A clear, published approach is a good sign.
- Conversion at the point of trade. Some platforms automatically convert the amount needed when you buy an asset priced in a currency you do not hold, so the order goes through instead of stalling while you arrange a transfer.
4. Keeping market access through the move
Relocation already strains attention. Losing access to your account, or having to learn an unfamiliar platform while you are finding a school or signing a lease, adds avoidable risk.
- A U.S.-based broker can be the most direct route to U.S. markets. Local banks and brokers abroad often offer U.S. shares at higher costs and sometimes don't offer U.S.-listed options at all. A U.S. brokerage that accepts clients in your country of residence can give you access to U.S. exchanges for stocks, ETFs, and listed options, subject to approval and the rules of your new home.
- Time zones change your trading day. Moving to Asia or the Middle East can put the U.S. session in your evening or overnight. Some brokers offer extended or overnight trading on selected U.S. stocks and ETFs, which lets you respond to news during your own working hours. Liquidity is typically thinner outside regular hours, so certain order types like limit orders should be considered.
- Breadth matters more once you are abroad. You may want exposure to your new country's market, to government bonds, or to funds that match your new currency. A single account with access to multiple international exchanges avoids juggling several providers.
- Protect your login before you leave. If two-factor authentication relies on SMS to a domestic number you plan to cancel, switch to an authenticator app first. Logins from a new country can also trigger security reviews, so let your broker know your travel dates.
- Keep a human option. Across time zones and during a move, the ability to reach a licensed broker to place a trade or resolve an issue is worth more than it appears on a feature list.
5. Borrowing against a portfolio across borders
Relocation often creates a short-term need for cash: a rental deposit, a car, a gap between one salary ending and another starting. Some brokerage account holders borrow against their portfolio on margin rather than selling holdings and realizing gains. Used carefully, that can be a bridge. Used carelessly, it can create unwanted leverage and increase risk in the portfolio.
- Compare the cost of borrowing. Margin rates vary widely between providers and by account balance. On a meaningful loan, the difference compounds quickly.
- Understand currency mismatch. Borrowing in one currency against assets held in another adds exchange-rate risk on top of market risk. A falling currency can trigger a margin call even if your investments hold their value.
- Know the rules on calls. If markets fall, you may be required to deposit additional funds at short notice or have positions sold, which is harder to manage mid-move. Margin trading is not suitable for everyone and can result in losses greater than the amount invested.
A pre-move checklist for your portfolio
- Tell your broker your destination country and get a written answer on whether your account can continue.
- Confirm which products you will still be able to buy as a resident of your new country.
- File the correct tax form (W-8BEN or W-9) and check whether a tax treaty applies.
- Take advice on tax residency in both countries before selling or transferring holdings.
- Set up funding in the currency you will earn in, and ask how conversion is priced.
- Move two-factor authentication to an app, and note your broker's international contact details.
- If you use margin, review your loan size and currency exposure before you travel.
- Keep records of your cost basis for every holding; you may need them for two tax authorities.
The bottom line
Moving abroad does not have to mean your investment portfolio needs to be impacted. The investors who come through a relocation smoothly are usually the ones who asked the right questions early: whether their account can follow them, what they will be allowed to trade, how their money will move between currencies, and how they will reach their account from a new time zone.
This is the problem Zacks Trade set out to address for international traders. Clients have access to 170 markets across 40 countries from a single login, can fund their accounts in multiple currencies with automatic conversion at the time of a trade, and can speak to licensed brokers when they need a human. If you are planning a move, it is worth checking whether your country of residence is eligible and comparing your options at Zacks Trade.
This article is for general information only and does not constitute tax, legal or investment advice. Tax rules depend on your individual circumstances and may change; consult a qualified professional in each country where you have obligations.
DISCLOSURES
This material is intended solely for U.S. residents and does not constitute an offer or solicitation in any jurisdiction where the firm is not authorized to do business.
The risk of loss in online trading of stocks, options, currencies, foreign equities, and fixed income can be substantial. Margin trading involves risks and is not suitable for all investors; trading on margin can result in interest charges and the possibility of losing more than what is initially invested. Options trading involves risks and is not suitable for all investors. Zacks Trade is a division of LBMZ Securities. Brokerage products and services offered by LBMZ Securities, Member FINRA and SIPC. Brokerage products are not FDIC insured, not guaranteed, and may lose value.
Comments
Essential services for your expat journey
Choose the best health insurance
Protect your health and get easy access to treatment for expats.
Plan your international move
Facilitate your move by getting a quote from our top rated movers.
Open a bank account that suits you
Discover the best international banks to manage your money securely.
International life insurance
Simple term-life insurance covering you & your family across borders
Further reading
You have everything you wanted abroad. So why aren't you happy?
Starting a business abroad: How to choose the right visa?
Importing a car to Mauritius: Is it really worth the cost?
Brownout: When working abroad no longer feels meaningful
Renting in Spain: Could your lease be automatically renewed?
What's on Mauritius this November?
Retiring after years abroad: Are you really ready to go home?
Moving to Saudi Arabia with your family? New visa rules make it easier
From Switzerland to Mauritius: Bernard Perroud on the realities of entrepreneurship
Join the community
Get regular tips and advice to make the most of your expat life